Investment Strategies: A Practical Guide for Beginners
Ask ten investors for their investment strategies and you will hear ten stock tips. Ask a hundred wealthy retirees and you will hear one answer: a boring system, followed for decades. An investment strategy is simply a set of rules for where your money goes, when, and why — and having one beats brilliant stock-picking nearly every time. Here is how to build yours.
Key takeaways
- A strategy is a system of rules; a stock tip is a guess.
- Asset allocation — your stock/bond mix — drives most of your returns. Set it by age and risk tolerance.
- Index funds beat most active stock-pickers after fees, and dollar-cost averaging removes timing stress.
- Tax-advantaged accounts (401(k)s, IRAs, solo 401(k)s) multiply a good strategy.
- Build your emergency fund first and rebalance yearly.
Why a strategy beats stock-picking
The market is full of people hunting the next 10x stock. Here is the uncomfortable fact: even professional fund managers, paid millions and armed with research teams, lose to simple index funds most of the time once fees are counted. Bankrate’s starting-investing guide makes the same point beginners miss: your behaviour and costs matter more than your brilliance.
A strategy answers four questions before money moves: what you buy, how much you risk, when you rebalance, and what makes you sell. Written down in advance, those rules protect you from the two emotions that destroy wealth: greed at the top, fear at the bottom.
Start with asset allocation, not tickers
Asset allocation is your split between stocks (growth, volatile) and bonds (steadier, lower return). Research has long shown this mix explains the bulk of a portfolio’s results — more than which specific stocks you hold. Your mix should reflect your timeline:
| Your stage | Sample mix | Why it works |
|---|---|---|
| 20s–30s | 90% stocks / 10% bonds | Decades to recover from crashes; growth compounds longest |
| 40s | 80% stocks / 20% bonds | Still growth-focused, with a cushion against shocks |
| 50s | 70% stocks / 30% bonds | Protecting what you have while staying ahead of inflation |
| 60s and beyond | 50–60% stocks / rest bonds | Income and stability matter more than maximum growth |
Match the mix to your temperament too: the right allocation is the most aggressive one you can actually stick with.
Index funds vs individual stocks: the core decision
An index fund holds hundreds of companies in one package — buy a total-stock-market index and you own a slice of nearly every listed company. Individual stocks are concentrated bets on one company’s future. For most beginners the comparison resolves quickly:
- Diversification: one index fund spreads you across sectors; one stock leaves you exposed to a single earnings report.
- Cost: broad index funds often charge 0.03% a year or less; actively managed funds and trading commissions cost far more.
- Effort: an index portfolio needs one annual rebalance; stock-picking demands ongoing research.
- Odds: after fees, most professional stock-pickers trail the index — and amateurs fare worse.
Dollar-cost averaging: the worked example
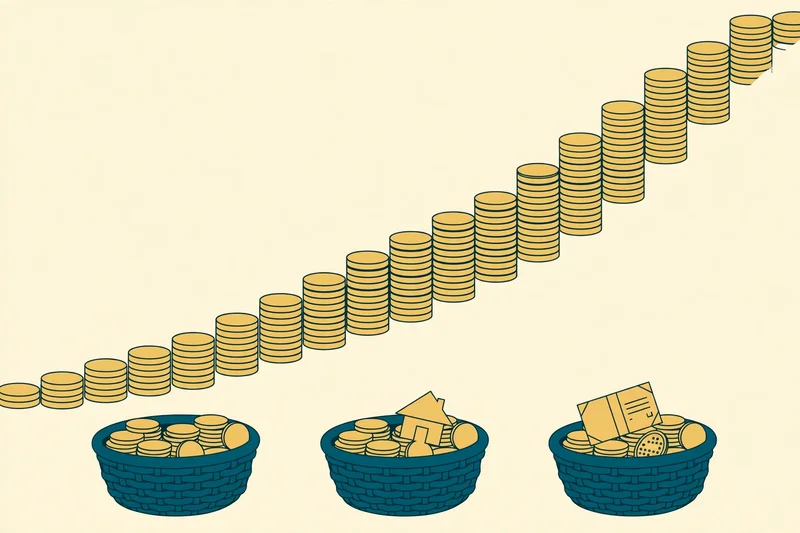
Dollar-cost averaging means investing a fixed amount on a schedule — say $500 every month — regardless of what the market is doing. When prices fall you buy more shares; when they rise you buy fewer. The result: no timing decisions, no panic.
Run the numbers: $500 a month for 30 years at a 7% average annual return — $180,000 of your own money — grows to roughly $610,000, with about $430,000 of that (over two-thirds) pure growth. Time, not timing, is the engine.
Diversify, then rebalance
Diversification means not betting your future on one company, one sector or one country: hold US and international stocks plus bonds. But markets drift — after a strong year an 80/20 portfolio may be 87/13 without you touching it.
Rebalancing fixes it: once a year, sell a little of what grew and buy what lagged, restoring your target mix. It feels backwards, but it locks in gains and holds your risk where you intended.
Use tax-advantaged accounts first
A strategy is only as good as where it lives. Tax-advantaged accounts let the same investments grow with less of the bill going to the IRS:
- 401(k) at work. Contribute at least enough to capture the full employer match — that match is an instant return no investment can beat. The IRS 401(k) rules set the annual limits and conditions.
- IRAs. Traditional and Roth IRAs add space beyond your workplace plan, with different tax timing — pay now or pay later.
- Solo 401(k). Self-employed? A solo 401(k) lets you contribute as both employer and employee, with unusually high limits. Our solo 401(k) guide walks through who qualifies (see also the IRS one-participant rules).
Order of operations: match first, then an IRA, then back to the 401(k). For how investing fits the bigger money picture, see our personal finance primer.
Emergency fund first, fees forever
Two unglamorous rules sit underneath every strategy. First, the emergency fund: three to six months of expenses in savings before a dollar goes to investing. A $4,000-a-month spender needs roughly $24,000 parked and untouched — without it, a job loss forces you to sell at the worst moment.
Second, the fee drag: a 1% annual fee sounds trivial. It is not. On $100,000 growing at 7% for 30 years, a 1% fee leaves you with about $574,000 — while a 0.05% index-fund fee leaves about $751,000. That is roughly $176,000 handed to the manager for the privilege of probably underperforming. Fees are the one guaranteed drag on returns, so choose the cheap option.
Three mistakes that wreck good strategies
- Panic-selling crashes. Investors who sold in 2008 or 2020 locked in losses and missed the recoveries. Your rebalancing rule, written in calm times, exists for panicked times.
- Chasing trends. By the time a trend feels obvious, the price already knows — trend-chasing is market timing wearing a better outfit.
- Overtrading. Every trade costs money and taxes; frequent traders earn less than buy-and-hold investors. Check your portfolio yearly, not daily.
Try it yourself
A strategy lives or dies by the numbers. Model your own dollar-cost averaging plan and see what decades of steady contributions can build.
See the retirement planning toolsSources & further reading
Strategy principles from brokerage and federal guides; all worked numbers are our own, computed in Python.
- Fidelity — Assembling an Investment PlanA brokerage’s step-by-step framework: goals, allocation, diversification and staying the course.
- Bankrate — How to Start InvestingBeginner-friendly walkthrough of accounts, funds and why behaviour matters more than stock-picking.
- IRS — 401(k) PlansThe federal rules on 401(k) contributions, limits and plan types.
- IRS — One-Participant 401(k) PlansWho qualifies for a solo 401(k) and how its contribution limits work.