Amortization Schedule: What It Is and How to Read Yours
Every fixed loan payment splits in two: interest for the lender, principal for you. An amortization schedule is the month-by-month table showing how that split changes over the life of your loan — and reading it is the fastest way to see what your mortgage really costs.
Key takeaways
- An amortization schedule is a month-by-month table splitting every payment into interest and principal, with your remaining balance alongside.
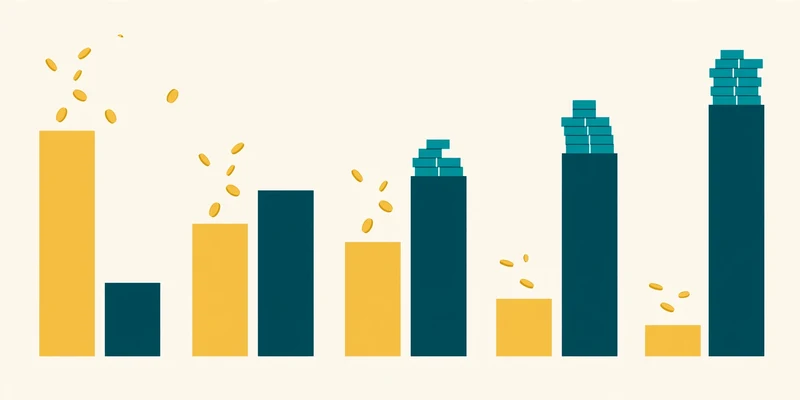
- Early payments are mostly interest: on $300,000 at 7.28%, payment one sends $1,820.00 to interest and just $232.64 to principal.
- By the final payment the split has flipped — $12.38 of interest and $2,040.26 of principal — while the payment never changed.
- The schedule reveals total interest: about $438,949 on that loan, far more than the amount borrowed.
- Extra payments rewrite the schedule: $200 more a month erases 87 payments and saves roughly $124,440 in interest.
What an amortization schedule actually is
With a fixed-rate loan — mortgage, auto, or personal — the lender does not simply divide the balance by the number of months. It applies an amortization formula that keeps your payment identical every month while the interest-and-principal split shifts underneath. The schedule is the written record of that formula: one row per payment, first to last. The CFPB’s plain-English explainer defines amortization as paying off debt in regular instalments over time — the schedule is where you watch it happen.
Every row carries the same columns: payment number, payment amount, interest portion, principal portion, and remaining balance. Read down the interest column and watch it fall; read down the principal column and watch it climb. The balance column tells you exactly what clearing the loan would cost at any moment.
How to read yours, line by line
Here are real rows from a $300,000 mortgage at 7.28% over 30 years — $2,052.64 every month:
| Payment | Interest | Principal | Balance after |
|---|---|---|---|
| 1 | $1,820.00 | $232.64 | $299,767.36 |
| 12 | $1,804.00 | $248.64 | $297,113.30 |
| 120 | $1,574.82 | $477.82 | $259,107.63 |
| 180 | $1,365.78 | $686.86 | $224,441.11 |
| 240 | $1,065.28 | $987.36 | $174,608.24 |
| 360 | $12.38 | $2,040.26 | $0.00 |
The payment column never moves, but everything else does. And note the shock at row 180: halfway through the loan, after 15 years of payments, you still owe $224,441 of the original $300,000 — the truth your monthly payment hides.
The great crossover: why interest comes first
Interest is charged on the outstanding balance, which is biggest on day one — so most of each early payment services interest. As the balance falls, less interest accrues and more of the fixed payment attacks principal. That slow handover is the whole drama of the schedule.
On our example loan, the crossover — the first payment where principal exceeds interest — does not arrive until payment 247, more than 20 years in. The payment never changed: $2,052.64 in month one and month 360 alike. What changed is what it buys. When comparing loans, remember the difference between APR and interest rate: fees folded into the APR shift every one of these rows.
The number that matters most: total interest
All 360 payments total $738,949.26 — for a $300,000 loan. Interest alone is about $438,949, roughly 146% of the amount borrowed: in cash terms, the house costs nearly two and a half times its price.
That figure is the schedule’s real gift: it turns an abstract rate into a concrete cost. A lower rate or shorter term rewrites the total dramatically — which is exactly what our mortgage calculator lets you test, taxes and insurance included.
Amortization schedule vs. payoff quote
Do not confuse the schedule with a payoff quote. The schedule is a projection: it assumes you make every payment exactly on time for 30 years. A payoff quote is what your lender says you owe today — usually the remaining principal plus a few days of accrued interest. If you have ever paid late, the two will differ slightly, because late payments shift how much of each payment went to interest. When you are about to sell or refinance, always ask for the payoff quote; the schedule is for planning, the quote is for paying.
What an extra $200 a month really does
Extra payments go straight to principal (confirm your servicer applies them that way). Each extra dollar kills the interest it would have earned the lender forever, so the effect snowballs. Add $200 a month and the schedule collapses: payoff in 273 months instead of 360 — 87 payments erased, about seven years and three months early — and $124,439.51 less interest, roughly $124,440 back in your pocket.
Even $50 or $100 a month moves the needle. The math rewards early principal above all else — which is also why paying mortgage points or refinancing early beats doing it late. Weighing a refinance instead? Our refinance rule-of-thumb guide walks through the break-even test.
Where to find your amortization schedule
Your lender or servicer must provide one — check your online account under statements or loan documents, or just ask. Want to model scenarios first? Bankrate’s amortization calculator builds a full schedule from your own balance, rate and term.
Run your own numbers
See how your rate, term and extra payments reshape the split — taxes and insurance included.
Open the mortgage calculatorSources & further reading
Definitions from federal and industry guides; all worked numbers are our own, computed in Python.
- CFPB — What Does Amortization Mean?The federal consumer bureau’s plain-English definition of amortization and how instalment loans pay down.
- Bankrate — Amortization CalculatorGenerates a full payment-by-payment schedule from your own loan figures.
- Corporate Finance Institute — AmortizationA technical walkthrough of the amortization formula and how each payment splits.
- WallStreetMojo — Amortization ScheduleWorked examples of schedule tables and the interest-first pattern explained.