VA Home Loan on Manufactured Homes: 2026 Rules Guide
A VA home loan on a manufactured home is absolutely possible — with $0 down, no monthly mortgage insurance, and competitive rates. But the property rules are stricter than for a site-built house: the home must be permanently affixed to a foundation, titled as real estate rather than chattel, and built to the federal HUD Code. Here is exactly what has to be true for the deal to close.
Key takeaways
- Yes, VA loans work on manufactured homes — but only homes permanently affixed to a foundation and classified as real property, never chattel.
- The non-negotiables: built on or after June 15, 1976 to the HUD Code, red HUD label and data plate intact, a permanent foundation with an engineer’s certification, and at least 400 sq ft (single-wide) or 700 sq ft (double-wide).
- Buy the home and land together, or set the home on land you already own — leased-lot homes generally do not qualify for the standard VA purchase loan.
- 2026 funding fee (verified on VA.gov): 2.15% first use / 3.3% subsequent use with no down payment. Veterans receiving VA disability compensation are exempt.
- Most deals fail on foundation certification or title issues, not credit — use a lender that regularly closes VA manufactured-home loans.
Can you use a VA loan on a manufactured home?
Yes — and on the borrower side it works like any VA purchase loan: a valid Certificate of Eligibility, the home as your primary residence, and your lender’s credit and income standards (the VA sets no minimum credit score). The hard part is the property: VA treats a manufactured home as eligible only when home and land function as one permanent piece of real property.
The non-negotiables: foundation, title, and HUD Code
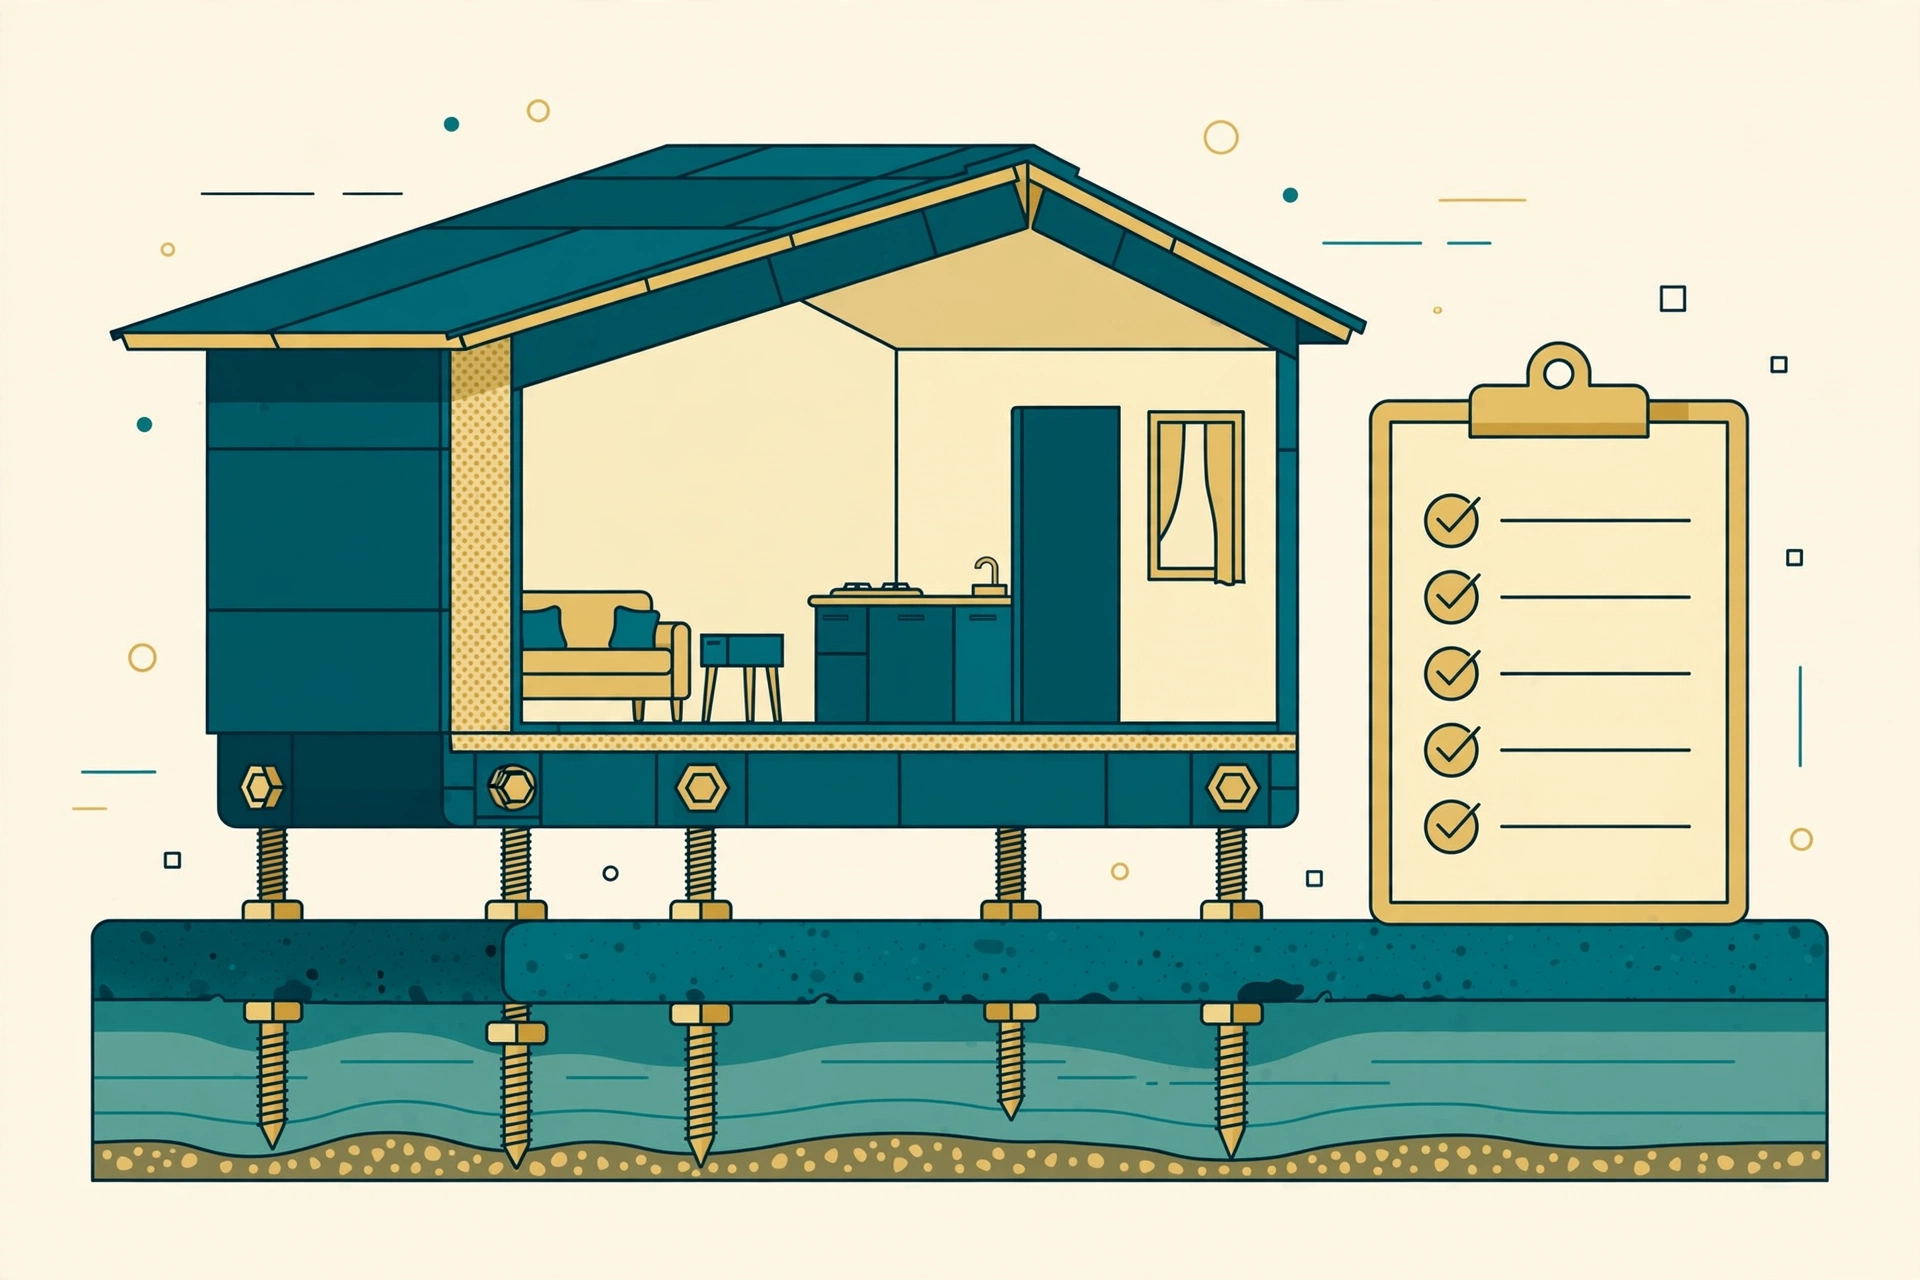
Permanent foundation. The home must be permanently affixed — wheels, axles, and towing hitch removed — on a foundation meeting local code and the HUD Permanent Foundations Guide, with a certification letter from a licensed engineer (a standard home inspection won’t do).
Real property, not chattel. Home and land must be financed together as one real-estate transaction, with the home’s title surrendered and recorded as real property. This is a cost issue too: homes titled as personal property need chattel loans, and the CFPB finds manufactured-housing borrowers pay higher rates than site-built borrowers.
HUD Code compliance. Built on or after June 15, 1976 — each section needs its red HUD certification label outside and the data plate inside. Missing tags can often be verified through the manufacturer or IBTS before you make an offer; an unverifiable home is permanently ineligible.
Size minimums. Per the VA Lender’s Handbook (Chapter 12): at least 400 square feet for single-wides, 700 for double-wides. Many lenders finance only double-wides, so confirm your lender’s overlay on single-wides early.
Do you have to own the land?
In practice, yes: a VA purchase loan can finance the home and the lot together in one transaction, or place a home on land you already own. A manufactured home on a leased lot generally cannot qualify, because without the land it cannot be treated as real estate.
One nuance: VA’s fee schedule lists a separate line for “manufactured home loans (not permanently affixed)” at a flat 1% — a distinct loan category that exists on paper but that very few lenders offer. And if your only previous VA loan bought a manufactured home alone, VA still charges first-time funding-fee rates on your next purchase.
The 2026 VA funding fee, explained
A permanently affixed manufactured home uses the standard VA purchase-loan fee schedule. Current rates, read directly from VA.gov:
| Down payment | First use | Subsequent use |
|---|---|---|
| Less than 5% | 2.15% | 3.30% |
| 5% or more | 1.50% | 1.50% |
| 10% or more | 1.25% | 1.25% |
On a $250,000 home with no down payment, first use, that is $5,375 — and the fee can be financed into the loan. Veterans receiving VA disability compensation, surviving spouses receiving DIC, and service members with a pre-closing proposed or memorandum rating are exempt entirely.
Appraisal and Minimum Property Requirements
The VA appraisal enforces the same safety, sanitation, and structural-soundness standards as any VA loan — sound roof, working mechanicals, safe water and sewage, adequate access — with extra attention on manufactured-home specifics: foundation compliance, HUD labeling, and any additions or structural modifications not built to code, which the appraiser must flag and which can sink the deal. For the full walkthrough, see our companion guide: VA appraisal requirements.
Rates and costs compared to site-built homes
The core VA advantages carry over: $0 down, no monthly mortgage insurance, and competitive rates — usually better than conventional or FHA pricing for the same borrower. Some lenders add a small risk premium on manufactured homes, and the thinner lender pool means less rate competition — shop at least two or three quotes.
Either way, it beats the alternative: a chattel loan on leased land, which CFPB data shows carries higher denial rates and higher rates. Evaluating rate-buydown offers? See what are points on a mortgage, and check the payment with our mortgage calculator.
Finding a lender that actually funds manufactured-home VA loans
Many VA-approved lenders simply do not finance manufactured housing, so ask directly: do you close VA loans on manufactured homes regularly? What are your overlays on single-wides, previously moved homes, and foundation documentation? Will you accept a PE-signed foundation certification? A lender that closes these monthly will know your state’s title-surrender paperwork and exactly what the appraiser will flag.
Bottom line
A VA home loan on a manufactured home is one of the cheapest paths to homeownership in the country — zero down, no mortgage insurance, real mortgage terms instead of chattel rates. The price of admission: a HUD-code-built home, permanently affixed to an engineer-certified foundation, titled as real property on land you own.
Running the numbers?
Estimate the monthly payment on a manufactured home, with taxes and insurance included.
Try the mortgage calculatorSources & further reading
Funding-fee rates and exemption categories read directly from VA.gov on 17 Oct 2026; property-rule details from VA’s lender handbook and the CFPB.
- VA.gov — VA Funding Fee and Loan Closing CostsCurrent 2026 funding-fee tables and exemption categories.
- VA Pamphlet 26-7, Revised — VA Lender’s HandbookVA's official lender handbook: manufactured-home loan purposes and real-estate classification rules.
- CFPB — Majority of Manufactured-Housing Borrowers Have Expensive LoansReal vs personal property titling and the higher cost of chattel loans.
- CFPB — Manufactured Housing Finance: New Insights from HMDA DataLand ownership drives titling; chattel borrowers face higher denial rates and rates.
- NewDay USA — VA Loan Property Types: Eligibility Rules by Home TypeHUD Code date, label/data-plate and 400/700 sq ft rules (from VA Handbook Ch. 12), plus lender overlays.