Does Renters Insurance Cover Storage Units?
Does renters insurance cover storage units? Usually yes — your policy's off-premises coverage follows your belongings to the unit, but only up to about 10% of your personal-property limit.
Yes — in most cases, renters insurance covers storage units. The standard renters policy (the HO-4 form) protects your personal property "anywhere in the world," so a storage unit does not strip their coverage (LegalClarity). The catch: belongings stored off your premises are usually limited to about 10% of your personal-property limit.
The 10% rule: how off-premises coverage works
Every renters policy has a Coverage C (personal property) limit, and a built-in provision extends it off your premises at a reduced sublimit. Most policies state it explicitly — usually 10% of your personal possessions coverage (Lemonade). Some carriers use 10% or $1,000, whichever is higher (Lemonade); regulators describe the typical range as 10% to 20% (WealthLedger, citing the Texas Department of Insurance).
The math: $30,000 of personal-property coverage means $3,000 for the unit (MoneyGeek), and $40,000 means $4,000 (WealthLedger) — a full unit of furniture blows past either fast. Two exceptions can lift the cap: belongings moved out because your home is being repaired or renovated and is unlivable (ValuePenguin), and items in transit to a newly purchased home, typically for the first 30 days (LegalClarity).
What is covered vs. what is not
Coverage follows the cause of loss, not the address. Standard named perils — theft, fire, smoke damage, and vandalism — are typically covered in a storage unit just as they would be in your apartment (Insurance.com; Lemonade). That named-peril structure works the same across property policies — our guide to what hazard insurance is explains the concept for homeowners.
The exclusions list is longer. Floods and earthquakes are not covered without separate coverage or an endorsement (Insurance.com; LegalClarity). Pest damage, mold, and gradual deterioration from humidity are typically excluded too — insurers treat them as maintenance risks, not sudden accidental loss (MoversCorp).
Theft claims have strings attached
Theft is the most common storage-unit claim, and insurers scrutinize it: many require evidence of forced entry, and nearly all want a police report filed promptly (EssyBenco). With no sign of a break-in, the loss may be treated as mysterious disappearance and denied.
Your deductible applies too: on a $2,400 theft with a $500 deductible, you collect $1,900. A loss below the deductible pays nothing.
High-value items hit sublimits first
Inside the 10% cap, certain categories carry their own special sublimits: jewelry, watches, coins, firearms, and cash (EssyBenco) — cash is commonly capped at just $100 to $200 (MoneyGeek). The fix is scheduling valuables individually via a rider or floater: broader protection for roughly 1% to 3% of the item's value per year, usually needing an appraisal or receipt plus photos (MoneyGeek).
When a separate storage-unit policy makes sense
Run the gap math: $12,000 of furniture under a $4,000 storage cap leaves you self-insuring $8,000 (WealthLedger). A standalone policy closes that gap in three situations: the 10% cap is far below the unit's contents (facility plans top out around $10,000 and run about $15–$30/month; independent policies can reach about $25,000 — Insurance.com; Lemonade); you have no renters policy (ValuePenguin); or the facility requires proof of insurance — most do, but their plans may exclude water and smoke damage your renters policy would have covered (ValuePenguin).
Owners play by different rules: stored belongings fall under a homeowners policy instead, and that insurance is typically escrowed into the monthly payment — see our guide to mortgage payments with taxes and insurance.
Document everything before you lock the door
Claims live or die on documentation. Build an inventory listing each item with values, prices, and receipts (Lemonade), then photograph or video every box and serial number — photos plus receipts are what turn a disputed claim into a paid one (Lemonade). Keep a copy somewhere other than the unit itself.
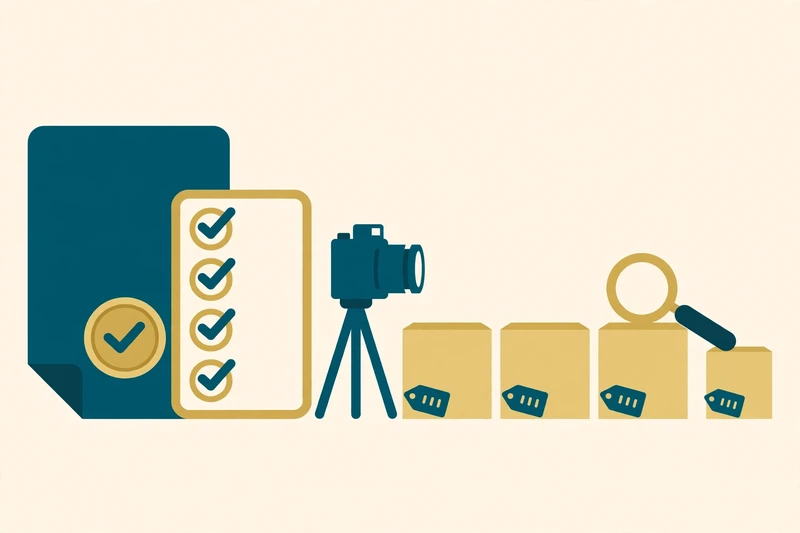
Label what is in each box — adjusters cannot value "miscellaneous" — and update the list whenever you add or remove something significant.
Key takeaways
- Yes, renters insurance usually covers storage units — capped at about 10% of your Coverage C limit: $30,000 of coverage means $3,000 for the unit.
- Theft, fire, smoke, and vandalism are typically covered; flood, earthquake, pests, and mold are not.
- Theft claims usually need evidence of forced entry plus a police report, and the deductible comes off the payout.
- Jewelry, cash, and firearms face extra sublimits — schedule genuinely valuable items individually.
- If the unit's contents far exceed the 10% cap, price a standalone storage policy.
Confused about named perils vs. open perils?
The same covered-risk logic decides what every property policy pays.
How hazard insurance worksSources & further reading
Figures checked against live sources on 21 Oct 2026 — each link below returned HTTP 200.
- Lemonade — Does Renters Insurance Cover Storage Units?10% or $1,000 sublimit; $50,000 → $5,000; deductible; cash $200; facility plans $15–$30/mo (curl: 200, 21 Oct 2026).
- ValuePenguin — Storage Unit Insurance: What Is It and What Does It Cover?10% rule; unlivable-home exception; facility plan exclusions (curl: 200, 21 Oct 2026).
- LegalClarity — Does Renters Insurance Cover Storage Units? Coverage LimitsHO-4 off-premises wording; 30-day transit rule (curl: 200, 21 Oct 2026).
- LegalClarity — Does State Farm Renters Insurance Cover Storage Units?Theft, fire, vandalism; $30,000 → $3,000; flood and pest exclusions (curl: 200, 21 Oct 2026).
- Insurance.com — Does Renters Insurance Cover Storage Units?Named perils; quake endorsement; plan limits (curl: 200, 21 Oct 2026).
- MoneyGeek — What Does Renters Insurance Cover?Cash sublimits; scheduling valuables (curl: 200, 21 Oct 2026).
- WealthLedger — Does Renters Insurance Cover Theft Outside the Home?Texas DOI 10–20% guidance (curl: 200, 21 Oct 2026).
- EssyBenco — Does Renters Insurance Cover Theft Outside the Home?Forced-entry and police-report requirements; high-value sublimits (curl: 200, 21 Oct 2026).
- MoversCorp — Does Renters or Homeowners Insurance Cover Moving Damage?Mold, pest, and gradual-damage exclusions (curl: 200, 21 Oct 2026).